Tuesday, January 15, 2008

Preparing for a Refinance (Purchase fundamentals too!)


Now is the time to prepare yourself for a refinance opportunity in the late spring or early summer. By preparing, I’m advising you to take some actions to ensure you get the best possible rate and program when it comes time to underwrite your loan. Banks are exceptionally tough right now and will continue to be a challenge:

> Credit: Make sure your credit rating is solid. A score of 720 is really desired. Improve scores by keeping credit debt under 30% of the available balance of any card. Don’t pile the debt on to one single card, spread it across a few and don’t open any new credit accounts, buy a car or anything that will ping your credit.
> Assets: Lenders like to see several months worth of “reserves”….so try to pad your accounts as best as possible; PERSONAL Checking, PERSONAL Savings, 401k, equity accounts….Liquidity.
> Tidy up: With more storms coming, keep the yard and home looking sharp so that when the appraiser does come, she’ll be able to show your house in GOOD shape and therefore be able to use the highest possible comps. Don’t open up any walls or have any construction going on when we go to appraise.
> Keep documentation: We’ll need copies of bank statements, recent mortgage and insurance statements when applying.
> Pay Attention to the market: " Tune in" to some of the different loan products to find the one that meets your needs. There are fixed rates, Option Arms, Home Ownership Accelerator loans, Hybrids. Notice if you’re cash-flow sensitive, rate driven or fixed rate oriented.


Call or email with any questions. Lots of factors that you can start to control NOW so that you're good to go. Your call. Let me know how I can help. I've got the goods: Pat Townsley, Mortgage Broker. 415-485-1776. http://www.ptre.net/

Friday, January 11, 2008

Soft Market Policies: More challenges for loans

New and tougher underwriting policies are on the rise in markets where the trend is for declining property values. The banks, in order to avoid future over-leveraged properties (via continually decreasing values) and maintain a reasonable equity position in the loan to value (to protect themselves)n have identified many geographical areas as "Soft Markets" and will require either MORE down payment on PURCHASE or on a REFI, you may be out of luck, outside of lender guidelines or even "upside down" on your mortgage. If it's Money Down, Upside Down, or Goose Down Pillows...Soft Markets are on the rise. One more reason to TAKE ACTION NOW on any refinancing and to sock away more money. I'm here to help and advise. Don't get left down and out. Pat Townsley, Mortgage Broker. 415-485-1776. http://www.ptre.net/

Wednesday, January 09, 2008

Once Great, She didn't see it coming...

The greatest vessel of her time that ever remanded sea, she was the mighty clipper ship, the “Sovereign of the Seas.” East Boston 1852, her frame of seasoned white oak, 12,000 yards of canvas tall, she crossed the line and doubled the horn again and again. No ship to date had stowed so much down in the hold. “We’ll weather any storm” the captain always said. After a magnificent run of seven years, she wrecked up on the Pyramid Shoals. America has quite a bit in common with this ship: Built against all odds, breaking records, weathering storms, thinking she, like the Titanic, like Rome, would never fail. American homeowners have leveraged as much equity from their homes as possible to buy “things.” Tapped, America is still spending more that we’re earning. How is that possible? Credit Cards. Soon, those will be maxed out as well. We’re looking at an epic possibility: Foreclosures, plus credit card bankruptcies, plus increasing unemployment, plus rising prices. Americans are mirroring the US Government’s fiscal procedures as a role model. Not cool. Time to batten down the hatches, tighten up the rigging, stow the gear and prepare for rough seas. Get your finances organized, your debts cleared and some padding in your pocket for the incoming tides. Only an ark will withstand the lowland shoals ahead. Please contact me for a free debt consolidation consultation. http://www.ptre.net/ . Pat Townsley, Broker.

Thanks to David Coffin for his inspiring accurate & historical tale telling and shanties including The Sovereign of the Seas from "Safe in the Harbour."

Tuesday, January 08, 2008

Why REFINANCE now? !

There are many reasons to start to refinance your existing finance now. Even if you have 6 to 12 months left on your tasty current fixed rate mortgage, there are some critical motivators in play right now:
1. Falling home prices may dramatically effect your home's value, decreasing your "loan to value" and making it more costly to refinance.
2. Lenders are tightening up their offerings, making it much more challenging to qualify for loans, even for people with perfect credit and good loan to values.
3. Market Saturation: This summer, the few banks that are left will be so overloaded with refinances and purchases, that they can use the pressures of supply and demand to actually Raise rates, even in light of the coming Fed rate cuts. You'll be caught in the maelstrom.
4. I'll save the rest of the reasons for the next newsletter or in a personal phone call with you to 415-485-1776. Sign up for my online newsletter at http://www.ptre.net/

Today's Market.

The National Assoc of Realtors revised their home sales outlook. Both new and existing home sales should bottom in the first quarter of 2008, then rise for the remaining three quarters. The housing starts outlook may continue to decline through 2008. WHAT DOES this mean to you? General homes being built right now aren't going to do so well, but "Resale" homes and homes coming on the market Starting March/April should see the bottom of the market.

  • 30 YR Bond +0.04 4.38%
  • 10 YR Bond +0.05 3.88%
  • 1 Year TBill 3.17%
  • 11th District COFI 4.23%
  • Prime Rate 7.25%
  • Discount Rate 4.75%
  • Fed Funds Rate 4.25%

  • I believe that there will be a massive inventory at the beginning of the 2nd quarter of 2008. The Fed will have lowered the interest rates enough that it will be a good time for people to get low priced homes with great rates. The only Rub is that lenders aren't giving out loans like they have in the past: It is MUCH harder to qualify for a loan. The sooner you start, the better positioned you will be to Purchase. Likewise, Refinance NOW while values are still relatively strong in comparison with the potential value drops in many markets. More information at http://www.ptre.net/

    Monday, January 07, 2008

    Back to Work: 2008


    Rate direction may be slightly up over last week. The bond market is losing some of last week’s price gains (prices falling, rates climbing) as global stock markets found buyers and money shifted from bonds to stocks. The posture in the stock market at the moment is toward purchasing, but it’s likely only technical, corrective trade will dominate today. There is little in way of economic reports this week which would otherwise create volatility.
    2008 is going to be one of the greatest Real Estate Buying opportunities in our lifetimes. For those who are considering Real Estate investing, now would be a good time to Get Ready. Call me for free loan consultations and free loan pre-approvals for properties in California: Pat Townsley, Mortgage Broker. 415-485-1776. http://www.ptre.net/

    Thursday, December 20, 2007

    Pop goes the Mortgage Industry: Washington Mutual

    WaMu just announced that they're tightening up the guidelines even more. As if it wasn't hard enough to do business today and get a loan, they've change the majority of their "stated" core products to require both 720 FICO score AND 50% Loan To Value max. That means: 50% DOWN PAYMENT. So, what WaMu is saying this week: We don't want any business. Any lender can cherry pick at Full Doc conforming loan....they're a dime a dozen. WaMu, like other lenders, is effectively pulling out of wholesale lending. That's one broker's opinion. I'm usually right. Where will you go for your next loan? How about http://www.ptre.net/, Pat Townsley, Broker.

    Credit Debt: Out of Control

    The credit markets are in difficult times. With online buying increasing in popularity and physical retail locations rarely seeing cash as a method of payment, the Credit Card is now the method of payment. Holidays often force people to purchase beyond their means out of guilt and obligation...and last minute deals. So, come 2008, there is going to be a LOT more credit debt on the average American. Give us enough rope and we'll hang ourselves with all this debt. If you have a home mortgage that allows you to pay off the debt, you might consider a refinance. It's not always the best bet or smartest play. I offer a confidential review of your financing opportunities. Leverage and position yourself sooner than later. Be PROACTIVE and not REACTIVE to the Credit Challenges ahead. Don't find yourself going over Niagra Falls in a boat with no oars. Mortgage lenders are TIGHTENING UP and you're not going to have many opportunities soon. Take Action! I'll guide you through the maze. Pat Townsley, Loan Consultants. 415-485-1776. http://www.ptre.net/

    Sign Up for my newsletter

    Happy Holidays to all. Trying to be as "Green" as possible moving forward into 2008, I am now offering my monthly newsletter in email format via my secure "no spam" website. I’m doing this to cut down on paper, postage and waste. Please take action to sign-up for my electronic newsletter at www.PTRE.net. You can do it in less than 15 seconds and I promise that this is my own private database; I will not "spam" or sell my information. Over the past decade, my printed personal newsletter has gone out to just over 1000 clients per month. Quick Sign up at http://www.ptre.net/. Thank you.

    More Mortgage Troubles on Wall Street: Bear Stearns

    "NEW YORK (CNNMoney.com) -- Bear Stearns swung to a quarterly loss Thursday and said it was taking a $1.9 billion writedown due to bad bets made on risky home loans, becoming the latest Wall Street firm to deliver disappointing quarterly results." Posted on CNN.com 12/20/2007.
    Not good news. Merril Lynch has had an even tougher time. WaMu has closed its "subprime" division. Wells closed its Wholesale 2nd's division. Citi, Chase, Wachovia/World, ALS, IndyMac and Countrywide have all reigned in their underwriting criteria. It's going to be tough times to get your next home loan. Those who ARE able to get into the market will do very well. It's a case of "the rich getting richer." We are seeing the early, but bold, warning signs of economic Depression. Time to buckle down and tighten up. If you're in an adjustable loan now, it's time to take advantage of the current low rates and lock in a long-term loan before prices make underwriting impossible. Pat Townsley: Solution Guy. http://www.ptre.net/. 415-485-1776

    Why Refinance Now

    Lenders are tightening up guidelines daily, so by refinancing now, you’re securing your life and buying serious peace-of-mind. I’ve been through absolute hell this past month with some of the simplest of loans falling apart and subsequent-damage control due to constant market corrections and changing guidelines. The deals are getting done, but with many more hoops-a-fire to jump through. The financial and credit sectors are in a lock-down. Americans aren’t saving. Consumer debt is out of control. Holiday retail sales numbers will be disappointing, banks will be closing branches or closing entirely. We’ll see decreasing consumer confidence and the media eating it up and skewing data for any political positioning for either side. Everything will be increasing in price from food to fuel, raw materials to transportation. Money won’t come easy anymore. Rates are as good as we’ve seen in over a year. If you (or anyone you know) needs to refinance anytime between now and 2009 and you have any concern that your home may now (or in the future) slide in value, the "Loan To Value" should be of great concern to you...right now. Secure a long-term position now before things change for the worse. We’ve only just hit the iceberg, and I’m the guy with the lifeboats. Let’s Talk. Captain Pat Townsley, Mortgage Navigator. http://www.ptre.net/. 415-485-1776.

    Action without Reaction

    Last Tuesday the Fed took another step at "helping" the economy by lowering the Fund Rate by a quarter of a percent. There’s also continued talk of the government and banks agreeing to "freeze" certain existing adjustable home loans as well as a bill on the table to eliminate "yield spread premiums" to lenders (in an effort to "level the playing field"). None of these will really help. Foreclosures and bankruptcies will tear us up in 2008, decreasing values and tightening guidelines will make refinancing harder in the months to come. It will make Purchase prices much more attractive, but you’ll need more money down in most cases. Get pre-approved before you shop! Purchase Loans throughout the State of California: Broker, Pat Townsley. 415-485-1776. http://www.ptre.net/

    New FLEXIBLE loan program


    I’ve got new loan programs rolling out from over 70 of the top remaining banks plus I’d like to introduce you to the "Home Ownership Accelerator" loan program. Let’s get a head start on 2008. If your loan is poised to adjust in the next 24 months, we should talk and put a plan and timeline together. Start your 2008 personal, family and business goals now and let me help you secure your future; Financing with Planning and Purpose, Not Pressure. Ask me about the Home Ownership Accelerator loan.
    Pat Townsley, http://www.ptre.net/ 415-485-1776.

    Dead Cat Bounce

    Dead Cat Bounce... A twisted definition of a visual occurance in a graph charting a time horizon. What we see is a rapidly declining market, then it appears to "hit" bottom, pop up a bit (maybe even a few times from "the bottom," then continue the decline. That's what we'll see in the real estate market ing 2008, probably a few times before we hit real bottom. There are many challenges facing homeowners, the US and the world. Our national economy has a huge effect on the global market. A rising tide lifts all ships, and the opposite as well. Who do you know who needs a solid mortgage solution? Please refer them to me. Pat Townsley, Mortgage Broker. http://www.ptre.net/. 415-485-1776.

    Sunday, March 25, 2007

    Shredded Bark: Poor choice for curb appeal


    You just spend a small fortune remodeling your home or an investment property. You've spent months, years working on the detail, the plans, the execution and the work. Magnificent work. Then, you come in and finsh off the landscaping, the curb appeal, the last final touch...with shredded bark. Folks, shredded bark looks like hell. It mats up, it turns brown, it pulls back and it's just looks cheap. It's a tool that people use to quickly gloss over a yard when selling something that hasn't been maintained. I'd recommend: Don't go cheap at the last second. Plan to finish with class to really make your home "Pop." Planted ground cover, pea gravel, river rock and at least "medium" bark adds a dimention of character, broader appeal and VALUE. American Soil Products in San Rafael has an inexpensive range of soil and rock. Also, a brief consultation with a landscape architect will be worth the investment. Put a nice cherry on the cake of your home.

    Monday, March 12, 2007

    SubPrime market crashes

    Yikes! Big time. This morning, the entire world is watching to see what happens with Sub-Prime lender NEW CENTURY. Last week Fremont Bank crashed and burned. "Conduit" lenders like Greenpoint Mortgage, ResCap and Paul Financial have recently pulled back their loan programs, especially their No Money Down 100% Financing offers. "Conduit" lenders typically sell their loans in the secondary market on Wall Street. They facilitate the mortgage agreements and package up loans to sell to investors. Today, we're seeing the beginning of what will be a new era of real estate subprime loans that will ripple throught the entire banking industry in terms of paperwork compliance, accountability, product offering and creative financing. There are still lenders offering 100% loans, but guidelines are tighter; credit scores, income verification, the whole package. The effect of lack of policing in real estate financing: This is going to hurt.

    Thursday, March 08, 2007

    JUST SOLD!


    Looking for real estate fixer opportunities? Folk, I've been telling you that they're out there, how to do it: Pearls, I'm giving you Pearls here. Since shouting at the wind hasn't worked, I've gone ahead and set the pace by buying my newest fixer project. This one will move fast. If you're interested, I'll tell you how to do it, and I'd even invite you over to work on it with me if you're in the Central San Rafael area in the next 60 days. After that, keep an eye out for it coming back onto the market as a beautifully restored single family home. Keep your eyes here for progress updates. This is going to be fun.

    Thursday, February 15, 2007

    Room Full of Gems

    Greetings business professionals. The Referral Institute is presenting a powerful networking efficency seminar in Novato CA on February 28th from 7 AM to 9:30 with Dawn Lyons and Trey McAlister. Referral-based, word-of-mouth is the ultimate sales program. Those who train in it are Master Salespeople. There is no exception to this rule. Other marketing tools like traditional advertising, public relations and web sites are certainly of value, particularly if they reinforce the word-of-mouth process. The experienced sales professional recognizes that word-of-mouth is head and shoulders above all other sales and marketing methods. For more information and a personal invitation, please contact me. Pat Townsley. 415-485-1776. http://www.PTRE.net. If you're too busy to attend, you really need to attend!

    The Market is ON FIRE


    What sells newspapers and makes for must-see news? FEAR. The headlines, the teasers, bumpers and stories are always worst case scenarios and how you're going to burst into flames and die from something that has no symptoms, no side effects and no cure. One this that is aflame is the mortgage market. Money is moving. If you know someone looking to buy or refinance a property, now would be a good time before the frenzy pushes you back out of the market. I'm available with great rates and programs for loan throughout California. A sweetheart loan is the 30-year fixed loan with 10-years with an interest only option. Great for owner occupied, units and investment homes. Flexible and secure. Pat Townsley, Mortgage Broker. 415-485-1776. http://www.ExcellenceInRealEstateFinancing.com

    Thursday, February 08, 2007

    National Wage Increase equals Inflation equals Higher Rates


    The argument is a slippery slope; If history is any indicator, the if the minimum wage increases, then the trend is for inflation to increase. When inflation rises, the Federal Reserve Board does it's job: INCREASES key short-term interest rates. The result is increases in all interest rates including mortgage rates. With a shift in the US political balance, one of the Democratic principals is to raise taxes across the board. This too will put additional strain on the US consumer, the everyday Joe, you and me. With a record number of 5-year fixed loans coming due in the next 18 months, positioning your refinance NOW with a new 10-year interest-only is a smart move for longer term planning. Don't wait until the rates start to go up. Get it going while they're attractive. Raising minimum wage sounds good in the short term, but in the bigger picture, it'll be a loss due to the cause and effect. Call me for the best loan scenario: Pat Townsley, Mortgage Broker. 415-485-1776. www.PTRE.net

    Tuesday, February 06, 2007

    100% Financing: Sensible planning & some assembly required


    "Double zero down": 100% financing for home buying MUST be done with planning. There are simple ways to get yourself simpled screwed if you don't know the components. This one goes out to the first time buyers in particular: When you have NOTHING to put "down" on a property, you're going to pay a higher price for lack of planning (i.e. not saving for a down payment). This will come in the form of higher rates. DO NOT forget property insurance and property taxes. Lender often avoid discussing these points to get their deal done, and there you are, ready to close escrow on your first house and need to quickly scramble for 10k in closing costs. Nice. Also, if you pay too much for your new home and the market is soft, you'll quickly be "upside down" where your value is less than you owe. There are GREAT 100% home loans for just about any buyer. Let me logically tell you how it's done, get your ducks in a row and get you into your new home. Don't gamble. I'll make sure your house has the advantage. Pat Townsley, Real Estate Financial Planner guy. 415-485-1776. http://www.ExcellenceInRealEstateFinancing.com . Your referrals are appreciated.

    Monday, February 05, 2007

    Economic status and predictions...


    This weeks economic calendar is a light as last weeks was heavy, with hardly any data coming out. Tuesday, Wednesday and Thursday's treasury auctions will be heavily watched, as will geopolitical events and any Fed Speak - which there is on Tuesday and Wednesday. Take note of the price of oil, it's approaching $60 a barrel, and much of our economic growth last quarter was attributed to lower energy prices. Bond prices are higher on what is a slow news day. Locally, the job market looks hot and the macro-economy is on fire. It's her, us, the little guys, who don't really feel the effects of money pouring in. Watch interest rates go through the roof if a new higher national minimum wage is put into effect. As the overall government make-up becomes more Democrat influenced, rates will really start skyrocket into double digits. History repeats itself. Now would be the time to secure your ARM financing or "fix" any loans that might have an adjustable component. The clock is ticking. Make the call: Pat Townsley, Mortgage Broker. 415-485-1776. http://www.ExcellenceInRealEstateFinancing.com

    Artie Gilbert: One of the greats!


    A Marin County icon passed away last week, Artie Gilbert, 61 years young. Recently married, a family man with a booming business and lifetime of friends, I knew Artie on two levels. We spoke not too long ago about my own real estate career and a possible switch for me into his office at Avalar Real Estate. We met a couple times in his office and had great conversations about this business and our previous years of friendship in: A bar. Not just any bar, this one was the place to be in Marin. It was called New George's, a historical landmark popularized in 1984 by owners Tom Hutt and Don Swartz. I came on board in the late 80's and eventually ended up running the show through 1996. Packed with 300 to 500 patrons on good nights to see the nation's top touring bands and local talent, Artie Gilbert was also along for this fast paced nightclub life. He'd come in and just light the place up with his energy, eventually promoting and managing a local pop dance fusion band called "About Face." We'd work the door together, promote the hell out of the band and pack the place...always with laughter and fun and a few bucks. Everyone loved Artie. At his service last Saturday, the San Anselmo Playhouse was packed with representatives from all walks of life and profession to share stories, kind words and love. Artie Gilbert, 1945-2007.

    Just Listed!


    In becoming a Realtor, I had to battle my own demons and overcome my fear of being grouped in with bunch of self-serving tools. After selling my first listing, I realized that it is a tough gig with a lot of work and brutal competition. I still marvel at the "Hey everyone, look at me" stuff in the industry, but that's the way it is. Reminds me of the classic stereotyping of Realtors by Annette Benning and Peter Gallagher in American Beauty. To that end: Hey Everybody, Pat Townsley JUST LISTED another home. "Another" home: too pretentious and assuming? Sorry. Well, if a condo is a home, the here's http://www.245bellam.com for your viewing pleasure. 3 bedroom, 1.5 bath, washer/dryer, two level corner unit. Very clean and ready to move in. Located in Central San Rafael, the charmer has low HOA fees of $281 per month and a view of something out every window. Proudly represented by Pat Townsley, Realtor: http://www.245bellam.com

    Business By Referral


    The most cost effective way of marketing and building your network of professional: Network Marketing. I'm on my soapbox and banging the drum after being in Business Network International (aka BNI) for the past year and a half. It's been a tremendous experience. Ask me anything? I've got a solution. CPA, CFP, CMT, Dr. DO, DDS, financial to the healing arts. It's opened up an amazing world. If you're interested in Network Marketing, expanding your business, I highly recommend that you seek out your local BNI chapter at http://www.BNI.com. If you're in Marin County, vist us online at http://www.BNISanRafael.com. You don't know what you don't know. I wouldn't be up on a blog without BNI's Ted Prodromou at Valiss Internet Solutions. http://www.Valiss.com (you can blame him for my rants!). Great people, professional results. Additionally, expand your knowledge at the Referral Institute (in the bay area at http://www.sfbayreferralinstitute.com)
    Need to know more? Contact Pat Townsley. 415-485-1776

    "Save $500 per month by refinancing!"


    Semantics folks, it's all semantics. I just received another opportunity to refinance one of my properties that stated I'd SAVE $500 per month by refinancing. What is does is actually "Free up" $500 per month in CASH FLOW on the pure cash montly payment, but it also defers off $900 per month, actually creating a $400 net worth loss per month or an annual loss in net worth of about $5000.00. If you're in an Appreciating market, then it might be justifiable, or if you're screwed against the wall for cash flow, working capital and/or have an exit strategy. Get honest quotes and solid financial advice. Pat Townsley, Broker. http://www.ExcellenceInRealEstateFinancing.com

    Jennifer's Law: California Sex offender battle


    In November 2006, California voters passed legislation to protect children against sex offenders. The action of "Jennifer's Law" has been morphing for years. In a nutshell on the most recent incarnation: No registered sex offender can live within 2000 feet of any school, playground, park, daycare facility and other places where children may go. Good in theory, but challenging in application. The hang up now is all about timing: When does it take effect? Effective immediately and forward, OR retroactively. There's the rub. Retroactive. If that was passed, then anyone registered as a sex offender and lives within 2000 feet of the aforementioned would have to move way. Also, Good in theroy, but difficult in application. There are many people with S.O. records from eons ago that was in no way a violent act or would even be prosocuted today, but it's on their records. Now, they have to move to the sticks. Then someone decides to build a park in their neighborhood and they have to move again. They can't live next to a national park. Where will they go? Who will enforce it? Will they be forced to sell their homes and at what loss and who will be sued for loss of equity in a forced sale? It's a messy scenario meant to protect children with too broad of a brush. Probably going to end up being unconstitutional. Find out more about your neighborhood, state and beyond:
    http://www.FreeCaliforniaSexOffendersList.org
    http://www.NationalAlertRegistry.com (aka http://www.MegansLaw.com)
    http://childsafenetwork.org
    You'll also note the total LACK of coverage on this issue. It's really being swept under the rug to try and get silent passage. I smell a conspiracy theory. Need disclosure when buying or selling a a home and a comprehensive neighborhood analysis? Pat Townsley, Serving California: www.ExcellenceInRealEstateFinancing.com

    Friday, February 02, 2007

    Don't fear the shadow.


    Groundhog day. DejaVu all over again. No need to hide if it's spring or 6 more weeks of winter: There are still great real estate opportunities to be had. Find the right property by being PRE APPROVED with your financing. Get your groundhogs in a row and your plan will come together. You can't act fast enough when the right deal comes and lays down at your feet. Free loan pre-approvals for purchases throughout California: http://www.ExcellenceInRealEstateFinancing.com
    Puxatony Pat, Broker, weatherman.

    Wednesday, January 31, 2007

    All the world is a Stage


    Well, it's been a while; The holidays, the clients, the kids, the fundraisers, the networking. Glad to be back at it.
    I recently went on a listing appointment. The "prospect" asked me if I thought his house should be "Staged." He had his furniture from the '60s, so it seemed appropriate for him if he was buying the home. However, home buyers are often blinded by empty spaces or dated looking seller furniture. As a builder, I think that I have some vision when it comes to looking at a home or property, however, I've found that most people can't "visualize" a home if it isn't laid out in a way that is warm and inviting. To that end, I've been working with a pair of professional STAGERS the past few months; one on a 6000 sq.ft. Victorian in San Francisco and a Condo in San Rafael. Two totally different properties and scope of work. Both have had rave reviews as to their presentation for representation. So, YES, I now recommend a consultation with a STAGER to all my clients. My referral to you this month is BELINDA BEEBE of Organize for Joy in San Rafael. She is a professional Organizer and Stager with a good eye. Some people say she's got two. Contact me for more information or to reach Belinda: Pat Townsley, 415-485-1776 and online at http://www.PTRE.net

    Wednesday, November 22, 2006

    Living Trusts


    YOU need to have your home in a Living Trust. It is a must-have security measure to protect your family assets. Avoid probate, legal challenges and leave a legacy that doesn't get trashed. In addition, you'll want to discuss other items with your attorney. WHAT? You need a referral for an attorney who will do a consultation for your and save your assets? Got it: Call BRENDAN BREWER for any California family and general business services. In Brendan we Trust: 415-492-0590.

    Saturday, November 18, 2006

    Market is Heating up again!


    The market is on the move again in Marin. While NEW construction spending fell dramatically in the past month, "Remodel" construction is on fire.. and many are selling their homes after their remodeling is complete, with a side note that builders have been BLESSED this year with a late start to the rains. There are a ton of projects that are still not closed in and weather tight: You got lucky!

    Back to the market: Get your loan pre-approved. It doesn't cost you a thing. You can get started with no obligation and no hassles at http://www.PTRE.net

    While at http://www.PTRE.net you can also request all the newest homes for sale sent to your inbox the minute they come on the market. Even if you're a few months away from doing anything, start watching the market now so that when you are ready to start shopping, you know what the comps are in the areas that you want to buy in. Information is power (if applied properly!). We've been seeing 90+ days on the market for homes. Now, I'm seeing some homes move in 30 days again, 14 days on a recent transaction in San Anselmo. Get in while it's still generally a Buyer's market. Don't get priced out agan! Call or email Pat Townsley for infomation. 415-485-1776. Full service real estate and finance broker. www.PTRE.net

    Friday, November 17, 2006

    Important questions to ask on a Purchase loan


    Here's a couple key questions to ask your mortgage lender prior to getting into contract on a new home purchase. For the point of this example, let's pretend that the Buyer is pre-approved for a 100% no money down home loan on an $800,000 home:

    Things to ask:

    • What is the current market rate on both first and 2nd?
    • Assuming an 800,000 purchase price, what will my total payments be given today's rate?
    • Is there mortgage insurance?
    • What are the points or fees?
    • What other fees and/or closing costs are there?( with no money down, how much do you still need in cash to close)?
    • How much can the Seller contribute back to me for closing costs?
    • Is there a pre-payment penalty or early termination fee?
    • How can I get a pre-approval letter to give to my Realtor to present with my offer?
    A good mortgage broker won't have to answer these questions as they would have told you all of these answers without you having to ask. Folks, Let's buy some real estate. Call me to get pre-approved for loans anywhere in California: 415-485-1776, Pat Townsley Real Estate Network, www.PTRE.net

    Thursday, November 16, 2006

    Short Sales Transactions


    Unfortunately, this term, Short Sales Transactions, does not mean Fast. This is when a property is worth less than the loans against the property and the seller cannot make up the difference between what the home sells for and the amount still owed to close the deal. This is time for agressive negotiations between the seller and the lender, and it needs to be addressed and disclosed prior to the house going on the market. It's a challenge. I can help. Pat Townsley, real estate consultant. www.PTRE.net

    Homes For Sale: It is time to buy


    The market is leveling off. This means the "scare" of falling values is normalizing with market supply and demand. Interest rates are holding relatively flat, taking the pressure and guesswork out of that component. Sellers looking to get out of Real Estate have put their homes on the market and they're generally sitting for 90+ before a sale or a price reduction. They're trying to get out before the market falls deeper. So, those homes are on the market. The other sellers will "get off the fence" as the market stabilizes... further saturating the market with inventory. It could turn into a buyer's frenzy...and in a frenzy, the top houses will start to see multiple offers...driving the market back up. We can't predict the future, but I know now is a great time to buy because we DO know what the market is like right now, and it's tasty; come get some. Free home loan analysis and approval and free home listings: http://www.PTRE.net, Pat Townsley, Excellence in Real Estate Financing. 415-485-1776

    Thursday, November 09, 2006

    Reverse Mortgages Available Here

    Federally guaranteed (FHA & HUD) REVERSE MORTGAGES are now available through Pat Townsley as California Mortgage Consultants. They'll put extra money in your pocket of retirees over the age of 62 years old. No more mortgage payments... now the banks pay You. Is it the right fit for you or your loved one? Find out: Call Pat Townsley at 800-646-5527 or visit me online at www.PTRE.net. Serving all of California.

    Monday, November 06, 2006

    Home For Sale


    How do you get to know the market and WHEN you want to buy? With basic analysis: I'll provide the Who and the How. You narrow it down by What, Where, Why. Getting specific on your neighborhood could be the most important. Location, location, location. Next; Size, style, amenities. The Why; To improve the quality of your life, put a roof over your head and invest in the future. What if you could have the freshest new home listings in your desired area sent to you when they come on the market? I offer the FREE service of just that. By knowing what is selling and at what price, you'll get to know the area, the prices and the activity. Knowledge is power. Click the Listings button or go to www.PTRE.net and let's get busy. Pat Townsley, Real Estate Broker.

    Wednesday, November 01, 2006

    Time to Buy!


    Time to get your loans pre-approved and get into the real estate profession. Times have changed and there is value if you work on it. Profit margins on Fixers is a bit less, but now other investors are getting out of real estate in search of higher yields in other markets. Great. Diversify that portfolio, check your current loan, get a loan pre-approved or secure your commercial property loan. Get it all at www.PTRE.net or just click on the APPLY NOW button. It's the simplest way to get your new loan approved or existing loan checked. Who do you know who are on the fence? Folks, it's time to get everything you've ever seen in the movies! You can do it. I can help. Pat Townsley, Real Estate Broker. 800-646-5527. www.PTRE.net

    Thursday, September 14, 2006

    0.25% interest rate. UNREAL!


    Is your house of cards about to crumble? Drowning in debt and need exceptional cash flow... and own a house with lots of equity and have an exit strategy? I just might have the solution for a fix. A ZERO POINT TWO FIVE (that's ONE QUARTER).... yep... 0.25% start rate fixed payments for 5 years. It's a monster of a negative amortization payment (deferred interest) at that start rate, but it takes a million dollar mortgage down to a couple hundred dollars out of pocket payment per month. You need equity...but if you're in the tightest cash flow situation in your life and you need total Flexibility, lowest payment and Debt Elimination, call me to discuss how this loan may work for you. Call me at 415-485-1776. See my September newsletter at www.PTRE.net for rate disclosures and APR and sample payments. Pat Townsley, Mortgage guru.

    The market is a buzz!


    Took the week off with the wife. 10 year anniversary. Went to Cape Cod and all around New England (I've had that "lobster stew by a window with an ocean view" song stuck in my head for years. Prices out there; not too far from our prices in California. It's easy to find homes from the $800k's to the millions. No problem. Market is buzzing from coast to coast. I did my Thursday Realtor duty of attending Broker's Open House Tours today in Marin. LOTS of inventory and buyers anxious to sell now. That's a good thing for buyers when you consider the interest rates are pretty stable now. So, buyers and investors: time to get your ducks in a row and call me for your pre-approvals and sign up to get the newest home listing on my website: www.PTRE.net (free listings of the newest homes on the market).

    Tuesday, August 29, 2006

    W.Y.S.I.W.Y.G.


    (In reference to Marin Fixer mentioned in previous blog (2 posts earlier, scroll down): Well, there it is. It's actually not quite the flaming piece of sh.... that I was expecting. Where else are you going to buy a home in Marin on a double lot that is actually habitable? I like it. As predicted, the hillside creates a serious challenge to the building and there is no parking. The upside is that it didn't "smell" like rott. There are many challenges, but in the scope of things, it's still a great deal for someone who is determined. Two ways to look at the fixer (mentioned in the previous blog)... Either $200,000 or $50,000 to improve. It all depends on who you are. You could also tear it down... but you'd be pretty screwed at that point... better to remodel. Do Note!: There is only a 1/2" water main coming in, so you'll have to fire sprinkle it... and you'll probably need 3/4" meter on there...and depending on the hook up, that could run into the mid Thousands w/ MMWD. Down and dirty, it's a deal waiting to happen. Call me to visit. www.PTRE.net. 415-485-1776. Looking to Partner up on a deal? I'm game. Let's talk.

    Commercial Space

    Interesting statistic... I guessed wrong. Marin has about 4.5 million square feet of commercial space (warehouse, retail, etc). It's reported that there is only 140,000 square feet currently available (versus Sonoma County at 10 million feet of inventory and 175,000 avail).
    Average Marin Vacancy rate is only 3% with prices ranging from $1.45 to $4.80 depending on location. Sonoma County has a 1.8% vacancy rate with prices from $1.25 to $3.30.
    As I drive around Marin, I see signs for Lease, Rent and Sale everywhere. It looked like Supply was on the busines owners' side, making negotiations easier for tenants. Apparently not so. Negotiating a solid lease with options for many years is critical in business vitality and investment terms. It's probably the single-most monthly expenderature that is out of your control once you set the terms in any business. You can control overhead, spending, advertising, sales, even energy costs...but you're bound by your lease. And make sure that you exercise your options in a timely fashion or you could be in a bad negotion point at expiration. Need other thoughts? I fund commercial buildings. www.PTRE.net. Pat Townsley, Broker. 415-485-1776

    Marin Fixer under 500k!!!


    The market is changing. Here's a little dandy that just came on the market. $395,000 in a neighborhood of $800,000 to $1,000,000 homes. I'm sure the previous owners ran out of money and steam.... probably in that order. So, what does this picture tell us?: Hillside, no handrail, upsloping lot, possibly no garage or sidewalk. Color indicates 1950's original construction, probable knob and tube electrical. So, the hillside gives us the most concern: Hydrostatic pressure over the years plus originally crappy foundation will probably find this thing "racked" and un-square. I'm sure there is plenty of unfinished work. Therefore, without seeing it, I can already smell the must, mold and fresh cut doug fir. You'll need cash and hard money to finanace this. No traditional bank will touch it... hence, the price. This is where cash talks and experience gets the deal done. The right person can put $150,000 into this beaut and flip it back onto the market in 60 days for $800,000. And that's how we do it downtown. Got the experience, cash and moxy? Let's go see it. Pat Townsley, Realtor and Hard Money broker. www.PTRE.net 415-485-1776

    Monday, August 28, 2006

    Selling California

    My good friend and associate Realtor John O'Donnell with Lifestyles Real Estate Inc in Santa Cruz just sent me a marketing piece based on a home he just sold. I thought... good for John, but why waste his postage on me. Of course, it's all about sharing information and showing activity. John's the guy I send clients to for Monterey, Aptos, Santa Cruz, Marina and that area. John and his familiy have a long track record of real estate excellence in that area. We have a reciprocity between each other.
    So, to bang my own marketing drum:

    Are YOU Looking for a Real Estate opportunities?
    I’m a Mortgage Broker & Realtor. One call handles it all.
    • Hard Money & Cross-Collaterailization leverage options.
    • Best wholesale rates from Top national A, B & C paper lenders.
    • Great ARMs, Fixed Rate, Construction Loans & Creative financing strategies.
    • Get free home listings at http://www.PTRE.net <(Take advantage of that! FREE for Marin, Sonoma, Solano & Napa)
    • House Hunt; SFR, Units, fixers, income properties, rehabs & probates.
    • Asset, credit and Mortgage Management consultations.
    • Fast, honest evaluations over the phone, by email or in person.
    Pat Townsley, Broker. 415-485-1776

    Thursday, August 24, 2006

    Reverse Mortgages versus Negative Amortization

    Reverse Mortgages are different than Negative Amortization in one fairly key point: In a Reverese Mortgage, your PAYMENT is also DEBT SERVICED by the "Negative Equity" payment...so you don't actually physically pay a Mortgage Payment every month... the payment is automatically drawn against your payment along with the full principal and interest (if you set it up that way). In a Negative Amortization loan you actually do make a Minimum Payment or "Start Rate" for "X" amount of years. Another key distinction is that Reverse Mortgages have an Age Minimum of 62 years old, loan to value guidelines and maximum loan amounts. They're Golden Years loans so that you can party hearty, take trips, see the family, live your life while keeping the house that you bought and living on the equity that you've put into it over the years. Do I have a Reverse Mortgage for you or your loved one? You betchya. Pat Townsley, keeping you in the pink. www.PTRE.net 415-485-1776.

    Enrolled Agents versus Certified Public Accountants


    There's no contest here when it comes to Verification of Self-Employment with a bank or lender. EAs an CPAs might do equally efficient in Tax Returns, but EAs are basically General Tax Preparers approved by the IRS, but not State Certified as Accountants. Without slamming EAs, as there are many great EAs, I absolutely recommend that you start searching for a CPA to do your returns. EAs, in my experience, are bookkeepers who want to provide more services but not willing to go through the bombardment of education, ongoing classes and state licensing that CPA endure.
    For those of you planning on buying or refinance a home and are self-employed... or thinking of being self employed, may I HIGHLY recommend that you find a CPA. File some form of Self employment income to generate a SCHEDULE C return and you'll have a much better shot at an easier loan transaction with the help of your CPA. I recommend you interview several CPAs to find one who fits your personal and business needs.
    Lastly, it is my belief that you're less likely to get flagged for a Tax Audit with a CPA than an EA, general tax preparer, or yourself. For the few hundred bucks to have a CPA do it...it's worth it. Make sure YOUR tax preparer is a licensed Certified Public Accountant. In California, call Michele Hassid, CPA at micheleh@eckhoff.com or Robert Edwards redwards@redwardscpa.com, or ask your associates for a good referral.
    For more info, contact me, your California State Licensed Real Estate Broker, Pat Townsley, 415-485-1776. http://www.ptre.net/

    Equity Reimbursement Notification


    I just received a check for $240,000, payable to ME, for "extra equity" in my property located in San Rafael. A real check, non-negotiable. Question. Do you think it would clear if I cashed it? It reads:
    "In compliance with the lending laws of the State of California, the equity reimbursement program was recently developed to reward homeowners for investing in high appreciating properties located in the 94912 zip code." This is my chance, finally, for reimbursement.
    Sadly, this is a freakin' scam and a half, but it will get the phone to ring, and the majority of the callers will get pissed and this will further be a black mark on the image of the mortgage industry. I really doubt that my Post Office Box located on Bellam Ave in San Rafael has appreciated $240,000. I've often thought of moving from my Post Box to a larger cardboard USPO tote or into one of the mail delivery trucks as my family is getting larger. I could probably make that move now with my new $240,000.
    Buyer Beward! Call me for the reality check. Pat Townsley, Real Estate Broker. 415-485-1776. www.PTRE.net

    Tuesday, August 22, 2006

    Construction: 3 Rules.


    One more thought on the topic: As my construction Mentor, Mark, always says "You can always be sure of one thing once you've started a project: It's going to be Harder, more Expensive and take Longer than you think." This goes for General Construction and Landscape Construction. Even the best plans end up costing more... especially when getting down to the "finish hardware." Friends; Do it once, do it right. Get your funds in place and be ready. People don't plan to fail, they fail to plan. I can help tailor your plan, get you the right referrals to get the job done right, and give you peace of mind. Pat Townsley. www.PTRE.net

    Why Remodel?...and where to spend your money!


    Remodeling not only improves your quality of life (upon completion of the project!) ...but it should also ADD VALUE to your home (which is an investment!). As I've mentioned before, ADDING Square Footage to your property will give you the highest return in equity. For resale and appealing to buyers, you should then focus on Kichen (most expensive "per square foot" cost but highest return on investment), then Bath...then Main/Great Room, Master Bedroom upgrades (least expensive). Of course, CURB APPEAL is what gets buyers salivating from the street, so Siding/Exterior, Windows as well as tasteful landscaping are also important. For me, I buy Worst House, Best Neighborhood. Don't buy Best House in Worst Neighborhood as you'll suffer "equity-wise" until the neighbohood's quality catches up to your value... and in that time, your home will be years older and need...a remodel! Providing FREE consultations on remodeling strategeies, cash-out for remodeling, construction loans and creative financing: Pat Townsley, Builder, Broker, and Financial Advisor to the Stars. www.PTRE.net 415-485-1776.

    Pre Payment Penalties

    Try to avoid them if possible. They're in place from the lenders so that they make sure they make their interest return on their investment by loaning you money. Now, if you absolutely know your new mortgage isn't going to be a candidate for refinancing in the next Three years, then it may be OK to take a prepayment penalty to lower your rate. Likewise, if you're getting a Home Equity Line of Credit (HELOC / 2nd Mortgage), then lenders have started "HIDING" the prepayment penalty in Semantics: They call it an Early Termination Fee. Basically the same exact thing as a pre-payment penalty... they just use ETF to get around the consumer's psychological barriers as well as disclosures in Federal form. Sometimes, prepayment penalties are "just the cost of doing business." Final note: Most Prepayment Penalties are TAX DEDUCTIBLE in the tax year that you PAY the Penalty. Call me if you need more information on prepayment penalties you might have on your existing mortgages or future loans. Pat Townsley, Mortgage Guru. 415-485-1776. www.PTRE.net
    I was just offered a 30 year fixed rate at 4% for Free!

    What does it all mean. How can one lender offer 1%, another 4% and the financial report says 6% and your bank or broker actually quotes you 6.5%? It's all in SEMANTICS, "grey area" marketing and reality. Most loans are 30 Year Loans, so they quote that, however, the fixed period varies and the Points you pay (or don't pay) can change the rate. Advertisers may say "30-year loan with a Fixed Payment" which is NOT a fixed rate....or a 30 year loan Fixed at "X" percent...(but fixed for how long???). Deceptive advertising gets the phone to ring, then you get the "bait and switch" in many cases. When the Financial Report says Fannie Mae/Freddy Mac offering a 30 year fixed mortgage at 6%, that's the bare bones wholesale pricing; it doesn't include the cost to actaully obtain that rate. Here's a sample of what I might see in one of my many market rate updates:

    Security Price Change Intra-Day
    FNMA 30 6.0% 99.97 00 BPS
    FNMA 30 6.5% 101.50 00 BPS
    GNMA 30 6.5% 102.22 00 BPS
    FNMA 15 6.0% 101.06 00 BPS
    US 10 YR 100.44 00 BPS


    This shows Me that at One Point I can give someone a standard 30-year fixed rate at 6.0%. It also shows me that at NO POINTS I can do it at 6.5%. This is your standard Full Doc convential conforming fixed rate loan. There are MANY options you can throw into the mix from Adjustable Rates to shorter and longer term loans, negative amortization, interest only and more. Need the real rates? Contact Pat Townsley, California State Licensed Mortgage Broker. 415-485-1776 at http://www.ptre.net/. Thanks.

    Saturday, August 12, 2006

    Economic Predictions


    Snakes On A Blog: If you've been receiving my newsletters, you'll see my forecasting has been pretty dead on as far as interest rates, The Fed, House Values and appreciation. I'm also going out on a limb to predict that the upcoming release of the movie "Snakes On A Plane" will be a block buster cult classic. Using the same logic, I also predict that we're going to see some interesting loan programs emerge in the next 5 months. We're going to see 50 year amorization loans and new hybrid loans where there will be an amalgam of neg-am loans and fixed rate interest only loans. There are two reasons: The industry must create new niches to keep loans in process and Two; the enconomy is strong with inflation leveling off. Fuel prices will continue to be a challenge, insurance rates will rise, educational costs going up, entertainment costs (ticket price to see Snake On A Plane will be $10 per ticket), travel cost will rise (security costs) and the Holidays are right around the corner. The economy needs to keep moving. Buying, selling, producing, importing, exporting. So, everything will get more expensive including an increase in wages to off-set that (a vicious cycle really)...and people will be needing to REFINANCE to make "cash-flow" to afford everything. So, look for 'Snakes' to make headlines, and call me before the mad rush to refinance. Get things planned so you don't stress. People don't plan to fail, they fail to plan. Pat Townsley, Real Estate Forecasting and Finance. www.PTRE.net. Licensed Broker #01234350. 800-646-5527.

    Friday, August 11, 2006

    Just Sold


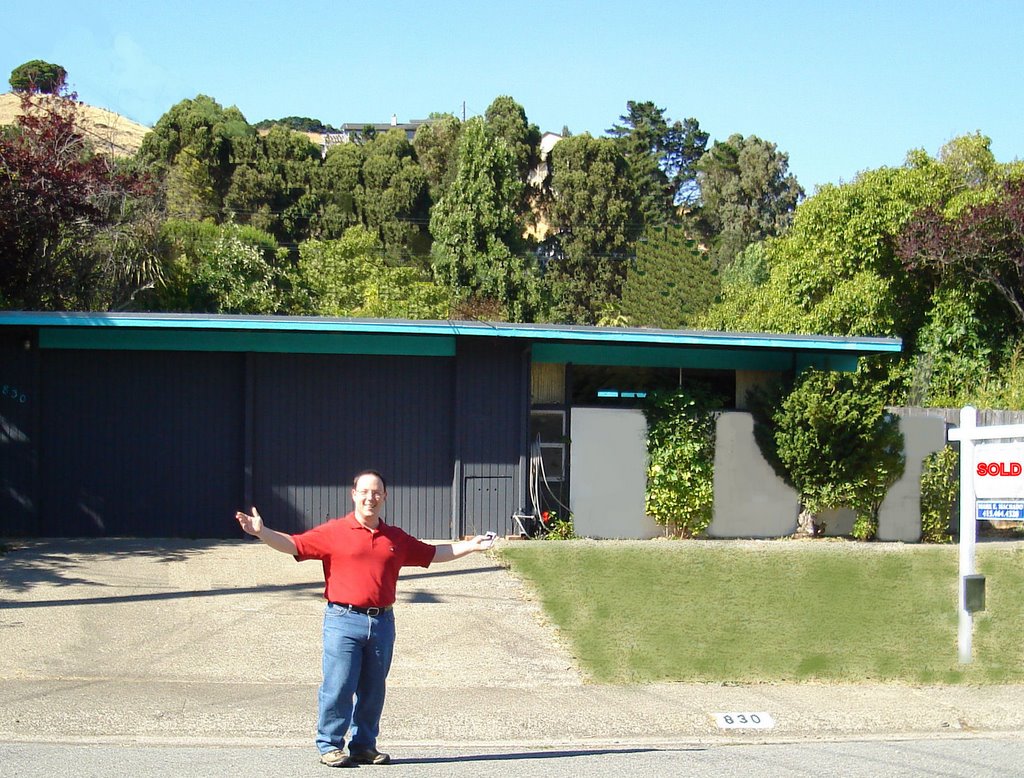
    Consolidating your point of contact can ease the stress in a transaction. I'm both a Realtor and Mortgage Broker. I can do both the financing and the real estate negotiation. This can not only make the process painless on you, it can also be a good leverage tool to quickly and efficiently make a better and more competitive offer, getting you the home you need. This recently sold Eichler on Penny Royal Lane in Terra Linda (North San Rafael) is a perfect example of that strategy working. Here we see new home owner, Kent Langley of RW Environments proudly standing in front of the home on closing day. We were the winner in a four party bidding war with the fastest and cleanest closing. We also did a stated income high LTV loan. Bam. Done. This fixer is well on it's way to seeing $100,000 of equity in less than two months due to a few basic improvements. We'll move the financing around (Mortgage Management) and improve the rate and term by using the new current market value upon completion of some landscaping. My axiom of Worst House in Best Neighborhood proves a winner again. Let me show you how to do it. I can do the financing or negotiation, or both... I just want to be in there somewhere! Pat Townsley, Excellence in Real Estate financing and acquisition. www.PTRE.net. 800-646-5527.

    Bad Credit

    There's not credit like bad credit. The good news is: It's repairable. Creditors (lenders; banks, credit cards, private parties, financial institutions, Visa, Amex, MasterCard)...they typically don't report to the credit bureaus (TransUnion, Equifax, Fair Isaac) if you're 30 days late on a payment on a credit card. It's when you get over 30 days that they start reporting that you were late in the previous 30 days. Not much you can do about that IF it is your fault. Collections are another downer. These things will haunt you...so if you've paid, make sure you keep your paperwork Forever. The original creditor will usually hire a Collections Agency to recover the money on their behalf, and that information can get sold off again and again, and I've seen clients with three agencies collecting the same debt to for a creditor who is long out of business. It can be a tangled web. Tax Liens are another issue. You've got to make sure those are paid correctly and get your Receipt and "Book number." Keep these payments forever as well. Lastly, no matter what: NEVER be late on your mortgage. A mortgage payment late will haunt your credit for years and years and really impead your Real Estate financing abilities. If you have credit issues, work with a mortgage broker who understands how to negotiate, navigate and improve your rating! Pat Townsley, Credit Master. www.PTRE.net, 800-646-5527

    Thursday, August 10, 2006

    30-year Fixed rate: SECURITY

    If you’re looking for Security, then you need to lock in your 30-year fixed rate if you haven’t already. Rates are attractive again, even in the "jumbo" category...back down to the low and mid 6%’s on the fixed rates. You may also consider looking at "paying a point" if you plan to keep your fixed rate mortgage longer than 5 years... which is really the point behind fixing the rate for 30 years. What a concept. Call me for rates! 415-485-1776, serving all of California; Pat Townsley, Mortgage Broker.

    Converting your Adjustable Equity Line to "Fixed"

    WARNING: Many lenders are offering to "Fix" your currently Adjustable Equity Lines to a fixed rate below the current Prime rate (at no cost, lower rate, fixed). Here’s a potential challenge: If you’re currently paying Interest Only on this line, and you roll it to most of the proposed Fixed loans, you’ll typically have to pay Principal in addition to the Interest payment. Point being, your payment may go up and you’ve lost the flexibility to pay down/recast the balance and payments and you’ve lost the ability to draw future funds (in most cases). Do your due diligence and get the facts. Every lender varies!
    SERVICE: I’m also hearing more and more about lenders and in-house banking lenders quoting one scenario, then upon review quoting an entirely different program and guidelines. If this happens, get the branch manager involved and express your displeasure with the dis-service. Customer service needs to remain Job One.

    California Median Home Prices for July 2006

    THE MEDIAN PRICE of an existing single-family detached home in California during June 2006 was $575,800, a 6.2 percent increase over the revised $542,330 median for June 2005, C.A.R. (California Association of Realtors) reported. The June 2006 median price increased 2 percent compared with May’s revised $564,440 median price.
    NATIONAL RATE: Thirty-year fixed mortgage interest rates averaged 6.68 percent during June 2006, compared with 5.58 percent in June 2005, according to Freddie Mac. Adjustable mortgage interest rates averaged 5.71 percent in June 2006 compared with 4.24 percent in June 2005. The median number of days it took to sell a single-family home was 46 days in June 2006, compared with 28 days (revised) for the same period a year ago. Buying or Selling? Patience! www.PTRE.net. Pat Townsley, Broker. 415-485-1776

    Federal Funds rate and Prime Rate

    August 8th, 2006: THE FED has given short-term interest rates a break from their climb. The Fed’s primary job is to curb the possibility of inflation. There are many tools, with the fastest reaction coming from short-term (aka Federal Funds) interest rate manipulation, which we tend to hear about as the Prime Lending Rate (Prime is 3 points over the Fed rate).

    WHEN PRIME RISES, we see an immediate increase in any adjustable rate loan. This includes any Prime based Home Equity Line of Credit (HELOC), standard ARM (Adjustable Rate Mortgage) loans and your Credit Cards. If you have a Neg-Am Option ARM type loan, watch out for additional deferred interest onto your principal if you’re paying the minimum payments. On Credit Cards, work on your highest interest cards first. If you have room on an Equity Line, check with me, your CPA or CFP as to your best use of leverage to pay those time bombs. If you hear friends, family or colleagues grumbling about adjusting rates, they’d be a great referral to speak to me about the many financing options that can improve their cash flow, security, net worth and lifestyle.

    Construction: What is a Story Pole?


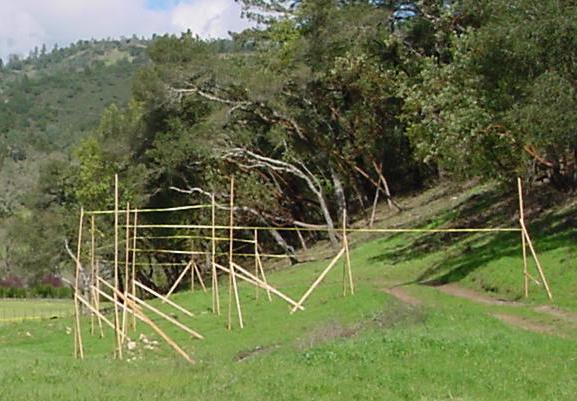
    Ever see those long sticks nailed to homes with yellow ribbon and orange tips? These are called Story Poles and these Poles tell the Story of your future. It is your friendly neighbor indicating the proposed heights and bounds of a new addition or new construction. If you’re seeing these poles, then the architectural plans are done, stamped and in to the local agency for design review and/or approval to build. If these poles tell the story that a giant wall is going up in front of your view, then you might have reason for concern. Other than that, the addition will bring value to their home and to your neighborhood. Most projects are well underway by this time of year to get "closed-in" before the rains. The picture shown here is a train wreck of an example of sloppy story poles indicating new construction on a slope. Story poles are used for both New Construction and Remodeling/Additions. Need remodel or construction financing? www.PTRE.net Pat Townsley, Construction and Remodel Loans for California. 415-485-1776

    Thursday, July 20, 2006

    Property/Casualty Insurance vs. Mortgage Insurance

    HOMEOWNERS insurance is required by mortgage lenders. It protects the homeowner from lawsuits like a "slip and fall" or damages from someone getting hurt on your property. It also insures your home for damages (like a tree falling into your home) or a fire. You can add on to your policy to have earthquake insurance and increased coverages limits including theft. You can also receive a discount from some companies if you insure home and auto and other lines. MORTGAGE INSURANCE is only to insure the BANK if you default on the loan. Mortgage Insurance is typically found when your first mortgage loan is larger than 80% of the value of your home. Call me (415-485-1776) to get out or avoid mortgage insurance. Call CLAUDIA CARDOZA at AAA (415-472-6700 x357) for your home and auto insurance needs. For commercial property and business insurance, call ANDY POPOFF at Farmers Insurance (415-472-1080). Keep your finances in the pink and review your policies, coverage as well as your mortgage annually. Pat Townsley, Consultant. www.PTRE.net. (415-485-1776).

    Wednesday, July 19, 2006

    Seller's credit to Buyer for NRCCs


    NRCC: Non Reocurring Closing Costs. These are the mechanical fees in any loan process. They're the real "hard costs" of doing a loan outside of the lender's compensation (fees/points/rebates). NRCCs include title and escrow fees, transfer taxes, reconveyances, wire fees, doc prep fees, notaray and a laundry list of little onesy-twosey "junk fees." For home buyers (if structured in the negotiation in the contract via an addendum), the SELLER can credit the BUYER for the closing costs. It can be a sticky thing. The goal is for the BUYER to keep as much CASH at close and basically "finance" the closing costs into the purchase price via the MORTGAGE. Figure most closing costs on an average Northern California/Bay Area purchase run around $8,000, wouldn't it be nice to not have to come out of pocket for these additional fees? The answer is Perhaps. Let's talk about strategizing your next purchase and keeping cash in your pocket at close. Pat Townsley, Real Estate Financial Strategist. 415-485-1776. www.PTRE.net

    Real Estate Referral Fees


    Mortgage broker and Realtors cannot legally take a commission or referral fee between each other. Same with escrow companies, etc. However, Realtors can refer business to each other and collect a referral fee or commission on the referral upon closing. We have standard Referral Agreements that are pretty common. I offer a 30% referral fee to Realtors who send me clients looking to buy homes in my territories (Marin, Sonoma, Napa, Solano Counties). Of course, I really focus on Central Marin properties and am well traveled in Sonoma and Solano. The reason Realtors would to this referral is to keep a small portion of a potential commission while ensuring that their client gets the best local representation by a Realtor who really knows the area. Looking to buy or sell in Marin? Call me. Looking to buy or sell somewhere else, Call me... I'll refer you to an excellent Realtor where you're looking to buy. Need to finance that purchase anywhere in California.... I'm the guy. Pat Townsley, Realtor and Mortgage Broker. www.PTRE.net. 415-485-1776

    Teamwork in a transaction

    I'm both a Realtor and a Mortgage Broker. Not many people can and will do both. I'm happy to do both, or either the Real Estate side or the finance side. When I do both, you get one point of contact and quite a bit more ease of transaction. I'm a micromanager, so regardless of how I'm involved in the transaction, I go above and beyond the call of duty to insure everything goes on schedule. I have a heck of a support team behind me from lender Account Executives, Escrow Officer relations and a vast referral network of professionals from construction to legal. I'm here to help and make things easy. Let's talk, let's do some business! Pat Townsley, Broker. www.PTRE.net. Making Real Estate really happen.

    1% home loan and no closing costs

    Warning; Danger, Will Robinson. Watch out for this often misleading type of advertising. The real goal of it is to sound so good that you call.... then you (hopefully) get the disclosure of how these loans work. Two primary keys to 1% loans and No closing costs: 1% is only a teaser type rate which is a Negative payment...so if you make that 1% payment, you're actually increasing the size of your principal balance in today's market. They're called Negative Amortization loans. The other point is No Closing Costs. There are always closing costs... you're paying them one way or another: either up front at closing, by having a higher interest rate and/or margin or by agreeing to a prepayment penalty on your loan. Need answers? I'm the guy: Pat Townsley, Loan consultant: www.PTRE.net toll free: 800-646-5527

    Wednesday, July 12, 2006

    When the _ _ IT hits the Fan

    Sometimes, when things go wrong (especially at the closing of a purchase transaction), the pressure is really "On." The one keystone in the purchase transaction is the Mortgage Broker or Lender. He gets blamed for anything that goes wrong. Everyone is counting on this guy to hold it together; Selling Realtor, Buyer's Realtor, Escrow officer, the Buyer, the Sellers, the insurance agent, home warranty people, movers, painters... families and communities are on the line. Even the best mortgage brokers have unforeseen train wrecks, where the wheels come off on funding day. That's where cool heads, fast action, relationships and experience prevail. What doesn't kill a mortgage broker makes him stronger. Call me for personalized service, non-stop service, great loans and on-time closings.
    Pat Townsley, Mortgage Broker to the Stars and putting out fires before they begin. Serving all of California. www.PTRE.net or call toll free at 800-646-5527. Close on time, every time.

    Accessing Information

    Folks, we're headlong into the Information Age. That's what we are as a society. Just one more step in evolution from Stone Age, Bronze Age, Industrial Age... and now...Data. Information is power. Embrace it, sort through it.... be the ball Danny. A powerful tool and soon to be a monster in the industry is the home valuation site called Zillow (Zillow.com). These guys are crunching tons of pieces of information in order to give you some form of value of property. They don't want to be Realtors. That's not the objective of Zillow and thier home "Zestimates." They're giving you free information in order to Advertise. They sell Ad Space. That's the game. They're the SuperBowl of home evaluations and neighborhood data. Watch for these cats to gain the home-field advantage as the Google of Valuations. Need another opinion on your home's value. Gimme a call. Pat Townsley, Realtor/Broker. www.PTRE.net toll free: 800-646-5527

    Tuesday, July 11, 2006

    Making a Million Dollar Offer

    Here we are in July 2006... lots of activity in the Real Estate market. I'm currently working on representing a client looking to buy in the Loch Lomond area (Pt. San Pedro and Peacock Gap) of San Rafael. Homes are fairly higher end out here... not much "fixer" opportunity, and homes are in the $1.1 million to $3 million range. So, there are many "comps" to set high prices. When evaluating a home for a purchase client, I go back 2 years in historical area sales within 10 miles, all sales on the subject street, and a one year "Active, Pending, Withdrawn and Sold" history to get a pulse on all activity... then we look for any challenges the subject property faces and try to come in with the most competitive and logical offer with a fast close, tight financing and try to avoid the ping-pong of counteroffers. Looking to Buy California? Pat Townsley, Realtor. 800-646-5527. www.PTRE.net

    Thursday, July 06, 2006

    Credit Challenges

    I'm sitting in my office with Calvin. His credit is a bit beat up from past delinquent payments and collections. To improve his credit rating, he can "Challenge" the ugly mark via a dispute with the credit agency which is reporting the delinquent. Not all three of the major reporting agencies report the same stuff, so you might see a Delinquent payment only from TransUnion and not the others. Try to resolve any other disputes directly with the source rather than collection agencies. Your credit blunders of years gone-by will haunt you forever... so take action to make sure your credit is clean. Seek professional advice. Many of the online credit scoring companies don't actually give you good information...and it's a waste of your money. Get the right help. Pat Townsley, Credit Medic & Broker. www.PTRE.net, toll free: 800-646-5527

    Tuesday, July 04, 2006

    Credit Scores; My take

    There are several "new" credit scoring methods now on the Internet. Some scores are over 900. What does that mean? Unknown. It's like Celcius, Absolute or Kevlin to the U.S. standard of Fahrenheit. In the Mortgage industry, we use the FICO (FICO is a trademark acroynm for Fair Isaac Company) score as the industry standard for all agencies. A Mortgage report merges information from the top three credit reporting agencies, giving you Three similar and close, but usually different scores based on your use of credit and the past history. We take the Middle of the three scores (the number, not the average) and use this to qualify your rate. The more you "run" or "pull" your credit report, the more Dings or Inquiries you'll have on your report. When considering a Real Estate financing opportunity (purchase or refinance), only let your #1 choice lender pull your credit, and avoid buying a vehicle, pulling your credit report, opening charge cards, increasing limits and/or ping-ponging debt. Let your lender (me) pull your report and we'll go over it together. I'm a master at credit repair, score improvement and debt structuring. Credit: It's Really important. Call an expert. Pat Townsley, Mortgage Broker. www.PTRE.net, 800-646-5527

    Terra Linda and the love of an Eichler.

    I grew up in an Eichler. Simple, classic, single-level modular to courtyard 1950's brain child of the man who's name is now legendary. Nice place to live....and I've seen them burn to the ground in about 3 minutes, I've seen them rebuilt and coveted to $1 million dollar super homes. In some circles, Eichlers are almost a cult...transforming them back into the 50's and 60's vintage style. A sweet Eichler; It's a bit better than having a really bitchin' Vega. Of course, when my mom bought our home in 1965 for $34,000.... who knew it would be in the $800,000 to $900,000 range some 40 years later. It would have been inconceivable. If you're thinking of buying or selling an Eichler, I'd love to discuss and broker that deal for you. I've been in just about every Eichler style in Terra Linda. I know 'em; I've replaced the radiant heat, windows, sewers, siding, you name it. What happens in an Eichler, stays in an Eichler. I'm here for your questions. Pat Townsley, Eichler native and Realtor. www.PTRE.net, local San Rafael: 415-485-1776

    Monday, July 03, 2006

    Information Security & your credit report

    Folks, you've got to watch youselves on sending information over the Internet...by fax, whatever. One social security number could screw up your entire life. A loan prospect just emailed me for the first time ever. He's a referral from a past client from three years ago....totally out of the woodwork. (Thanks for the referral Don!). Anyway, this new prospect emails me his bank statements, Social, paychecks and W2s on the very first email. Kinda chilling. All this information, basically Blindly send to me without any previous contact. I've got his name, address, social, DOB, where he works, the hours he works, all his personal banking and savings info. Imagine if this email landed up somewhere else by accident. So, make sure you've got a relationship/rapport before you send you life over the Net. Pat Townsley, Broker and associate Crime fighter. www.PTRE.net

    Refinancing on the Cash Flow ARM

    I've been happily busy with meeting clients at their homes this past week to discuss the various refinancing options available at this time. A lot of the time, I recommend NOT refinancing as their current low, ARM or Fixed rate is better than the alternative of Refinancing. In several cases, Refinancing is a great alternative to improve their overall financial picture. The ADJUSTABLE RATE MORTGAGE (aka A.R.M.) can be a nice solution for a client where their debts are out of control and their income is luffing. Call or email me with any questions for your particular situation. Remember, your financial health isn't healthy if you're pumping cash in one side and bleeding it out thru another. Balance is sometimes hard to achieve, and we often put blinders on to where we're losing blood. So, let me help; The doctor is IN. www.PTRE.net, toll free 800-646-5527. Pat Townsley, Financial trauma doctor.